Internal Revenue Service
S corporation returns and shareholder statements
Choose the edition for the corporation’s original tax period. Use the IRS filing instructions and give shareholders the required Schedule K-1 and other applicable statements. Complete identifying, financial and shareholder details through the filing channel.
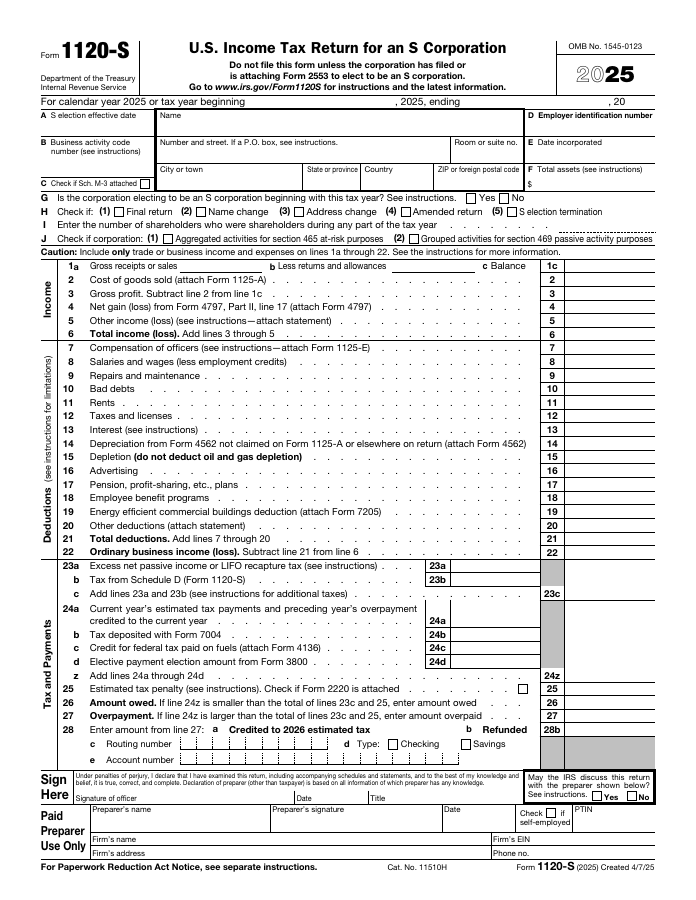
Confirm election and tax period
Check whether the Form 2553 election covers this tax year and whether it has been accepted or terminated. Review eligibility and late-election procedures for a new corporation. Eligibility depends on shareholder number and type and on stock rights, with specific exceptions for qualifying trusts and exempt organizations. Loss of eligibility generally ends the election on the day the corporation ceases to qualify, subject to statutory relief. Three consecutive years with accumulated earnings and profits and excessive passive investment income can cause a separate termination starting the following tax year. An S corporation may need to file even when there was no activity. Income can pass to shareholders, and certain items can produce corporate-level taxes.
The ordinary filing date is the 15th day of the third month after the tax year ends; holidays, weekends, disaster relief and extensions can change the filing date. Check the approved or permitted fiscal year. A short year beginning and ending in 2026 can use the 2025 edition if the 2026 return is unavailable by its due date. Enter the actual dates on the return and each shareholder’s Schedule K-1. Apply the law for the 2026 period, including changes that postdate the printed edition.
Returns, statements and corrections
Use the corporation return and Schedule K-1 for the same tax year. Each shareholder receives the relevant statements; check the separate requirements for international Schedules K-2 and K-3 and shareholder basis reporting. To amend, use the original year’s corporate return, indicate the amendment and furnish corrected shareholder information when it changes.
Federal e-file rules can apply when the corporation must file at least ten returns in aggregate. Check applicable exceptions and filing channels. If mailing, use the chart for the location of the principal business, office or agency, assets and any Schedule M-3 filing.
When S status ends
On the corporation’s last return, follow the final-return and shareholder instructions. When the S election ends, report the election termination as instructed. A company can continue as a C corporation after S status ends. The event and effective date can require separate short-period filings. If the S election ends during the year and the corporation continues as a C corporation, the S short-period return generally shares the due date of the C short-period return, including extensions. A section 336(e) qualified stock disposition generally follows its separate third-month deadline. A dissolution or liquidation plan can also have a Form 966 requirement.
State recognition of an S election, state or city entity taxes, shareholder residence, nonresident withholding, pass-through elections and state amendments can differ. Check the agency for every applicable jurisdiction.
IRS return and instructions · IRS election procedures · Closing a business