Internal Revenue Service
Partnership returns and partner statements
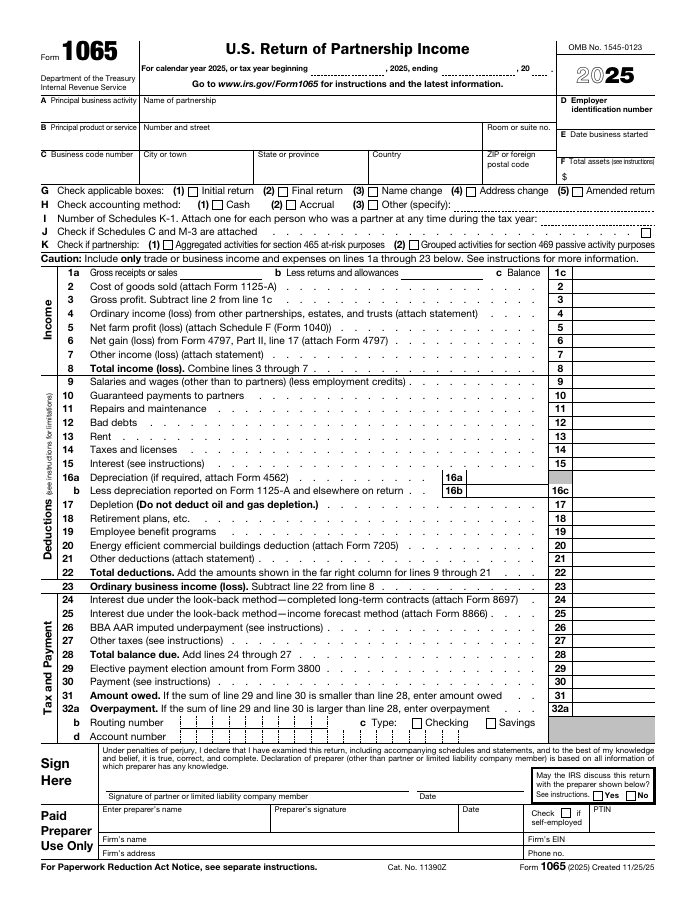
Use the federal return and partner schedules for the partnership’s accounting period. For a period beginning in 2025 and ending in 2026, use the edition for the year in which the period began. The IRS also permits the 2025 return for a period shorter than 12 months beginning and ending in 2026 if the 2026 return is unavailable by its filing due date. Enter the actual 2026 dates on the return and each applicable Schedule K-1 or K-3, and incorporate applicable legal changes. For a correction, confirm the edition originally filed before choosing an amended return or administrative adjustment request. Check the IRS instructions for the filing year and each state where the partnership does business or its partners may have a filing obligation.
Does the entity file?
A domestic partnership generally files unless it received no income and incurred no expenditure treated as a federal deduction or credit. Special rules apply, including to qualified opportunity funds. Limited partnerships and multi-member LLCs first determine their federal classification, including a corporate election. Married co-owners should check the qualified joint venture requirements, including material participation, and the separate community property rules.
A foreign partnership can have a U.S. filing obligation from effectively connected income or U.S.-source gross income. The exceptions for limited U.S. activity or no U.S. partners have different conditions, including withholding and reporting. Forming abroad or having a foreign partner does not resolve that question. An exempt section 501(d) religious or apostolic organization uses the applicable Form 1065 instructions and allocates its taxable income to members as dividends, including undistributed amounts. Its annual exempt-organization information return must be filed electronically. Members receive their dividends in K-1 box 6a. The organization makes its annual return, schedules and attachments available for public inspection, except the member K-1s. IRS section 501(d) guidance.
File and deliver partner statements
The ordinary deadline is the 15th day of the third month following the end of the partnership tax year, adjusted for weekends and legal holidays. Use the applicable instructions for extensions, special situations and disaster relief. Use Form 7004 when eligible. Send each partner the applicable Schedule K-1 and determine whether international Schedules K-2 and K-3 apply.
Check both electronic filing rules. A partnership required to file at least 10 returns of any type covered by the aggregate rule in the calendar year generally must file electronically, even with few partners. Partnerships with more than 100 partners have a separate electronic filing rule. Examine applicable waivers or exceptions before mailing. The mailing address and payment procedures may depend on the partnership’s principal business location, assets and filing requirements.
Virginia partnerships and owner statements
A qualifying business with Virginia operations or Virginia-source income generally files state Form 502 and provides Schedule VK-1 to owners. Check nonresident withholding and any annual pass-through entity tax election separately. Federal K-1 delivery does not complete the Virginia filing.
A final federal adjustment can start different deadlines for the partnership and its direct or tiered partners. Virginia has its own election to pay and its own federal adjustments report. For a short 2026 period, confirm the accepted Virginia edition before filing.
Virginia Tax filing guidance and Virginia partnership adjustment law.
Tennessee partnership filings
Form 1065 and Schedule K-1 are federal documents. An ordinary general partnership is generally outside Tennessee franchise and excise tax, but an LLC or limited partnership registered or doing business in Tennessee generally must consider Form FAE170, even when it files as a partnership federally. A corporate owner of an ordinary general partnership can itself have Tennessee filing obligations through the partnership’s activities. Check the entity’s legal form, business activity and any applicable exemption separately from the residence of a partner or the address used to mail a federal return.
For an out-of-state entity, Tennessee’s statutory bright-line receipts test requires receipts to exceed the lesser of $500,000 or 25% of everywhere receipts; the corresponding property and payroll amounts are $50,000 or 25%. Equality alone does not meet that test. Other connections, including systematic Tennessee business or licensing an intangible for use there, may still establish nexus. See the legislative text of § 67-4-2004(47).
A family-owned LLC or limited partnership does not qualify for exemption on its name alone. Check the applicable ownership and passive-income or farming tests and file FAE183 for the initial claim and renewals. The ownership amendment effective July 1, 2026 changes the treatment of relatives, qualifying trusts and estates; do not apply it automatically to a prior year. For an IRS income revision affecting state franchise or excise tax, Tennessee specifies its Federal Income Revision form and supporting records. In the Department of Revenue’s Franchise & Excise Tax forms list, look for “Franchise and Excise Federal Income Revision.” Confirm the actual adjustment and taxpayer before using that process for a federal partnership AAR or a partner-level adjustment.
Rhode Island partnership returns and adjustments
A general partnership required to file RI-1065 can owe no annual fee and still have to file the return, issue state member statements and account for nonresident withholding. An LLC or limited partnership may owe a fee. Rhode Island’s annual entity-level tax election is separate from the federal return. For tax years beginning in 2025 or later, the state statute defines the owner’s credit as 90% of their share of entity-level tax paid.
A federal partnership audit or administrative adjustment can require a Rhode Island supplemental return and payment within 180 days after receiving notice of the final adjustments. Different rules apply to an ordinary amended individual return or a corporate adjustment.
Rhode Island partnership forms · Rhode Island supplemental returns
Delaware partnership and member returns
For a business classified as a partnership, Delaware-source income or loss can require a state PRT-RTN and partner information on PRT-PSI. Where the partnership has mixed-state activity, review its separate accounting or apportionment. A Delaware organization that has no Delaware-source income or loss should separately check its annual registration tax. Qualifying nonresident partners may elect the Delaware composite return under its participation rules.
The IRS short-period and correction documents here serve the federal filing. Check the Delaware edition and state reporting of adjustments for the actual period, including any partner-level reporting following a federal audit. Delaware forms and instructions · Delaware pass-through statutes
Washington partnerships and their owners
Washington business and occupation (B&O) tax looks to the entity’s activity, physical presence, organization, commercial domicile and Washington-sourced receipts. The partnership’s federal filing office and an individual partner’s address answer different questions. Capital gains allocated through a partnership can have individual Washington tax consequences, depending on the asset and the owner’s circumstances.
Beginning January 1, 2026, check the revised Washington investment-income deduction. The incidental-income test generally requires investment income below 5% of worldwide gross income and has exceptions. Separate profit distributions, service payments and the entity’s own investment activity. Washington nexus statute, individual capital gains statute and investment-income deduction.
Correct a previously filed return
For a section 501(d) organization, confirm whether the filing being corrected was its exempt-organization annual report or a separate partnership return. The use of Form 1065 alone does not answer that question. For a partnership, first check whether a timely superseding return is available. For a later correction, determine the audit regime for the reviewed year. A partnership validly outside the centralized BBA regime follows the amended-return procedure. A BBA partnership ordinarily uses an administrative adjustment request. Form 1065-X can be used for a permitted paper AAR. Electronic AARs instead use Form 1065 with Form 8082 under the IRS instructions. Follow the separate partner-statement and imputed-underpayment rules.
IRS Form 1065 and instructions · IRS administrative adjustment requests · Prior-year forms