When a payment is reportable
Identify the payee, calendar year, payment category and how you paid. Personal payments generally fall outside business information reporting. A card payment or qualifying third-party network transaction subject to section 6050W belongs to the payment settlement entity’s reporting process. Avoid reporting that transaction a second time on 1099-NEC.
For 2026, report qualifying service payments totaling at least $2,000 to the same nonemployee. The prior general threshold for 2025 was $600. Include qualifying parts and materials supplied in connection with the services. Apply the rules for the payment year.
Employee wages belong on Form W-2. The form you issue does not decide worker status. An incorporated payee can still require reporting in specified cases, including qualifying fees for an attorney’s own services. Distinguish those fees from attorney gross proceeds on Form 1099-MISC. Excess golden parachute payments have a separate 2026 Box 3 rule.
If you withheld federal income tax under the backup-withholding rules, report the payment and withholding regardless of amount. Another separate rule covers at least $5,000 in qualifying direct sales of consumer products for resale. Use the appropriate indicator on either 1099-MISC or 1099-NEC and avoid duplicate reporting.
Use the boxes for the payment year
For 2026 the form separates nonemployee compensation in box 1a from cash tips in box 1b, the Treasury tipped occupation code in box 1c, and overtime compensation in box 1d when applicable. Follow the IRS instructions for which amounts and codes to include.
Get taxpayer details directly from the payee through the appropriate secure process, such as Form W-9 when applicable. The download here is blank. You do not enter the payer’s or payee’s TIN on Document.com.
2026 IRS form instructionsOfficial 2026 PDF
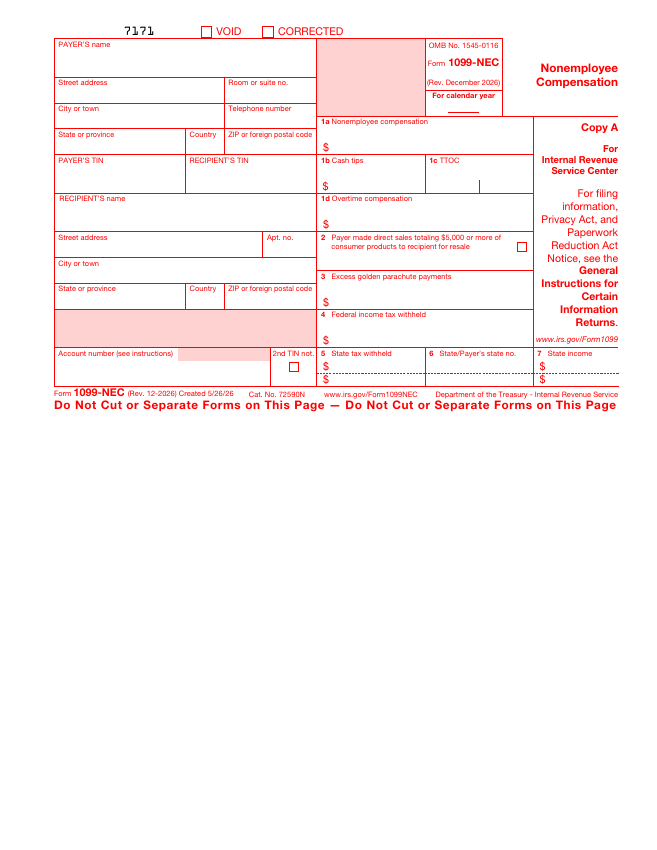 Open the complete 1099-NEC PDF for 2026
Filing and recipient copies
The usual federal filing date is January 31 for paper and electronic filing. Statements generally go to recipients by January 31. If a due date falls on a weekend or applicable legal holiday, check the next-business-day rule in the IRS instructions.
For returns required to be filed on or after January 1, 2024, electronic filing generally applies when the filer reaches 10 covered information returns in aggregate across types. Check applicable exceptions and waivers. For 2026 information filed in 2027, the IRS identifies IRIS as its electronic intake system.
2026 IRS general filing instructionsFiling questions
Can I file the downloaded Copy A on paper?
Do not print the red Copy A from this PDF and mail it to the IRS. It is provided for information and cannot be scanned for filing. Use the IRS electronic filing procedure or, if paper filing is permitted, obtain official scannable Copy A forms and the applicable Form 1096 transmittal. Follow the form’s instructions for recipient copies.
How do I correct an earlier filing?
Start with the payment year on the original return and its applicable form revision. For paper corrections follow the IRS correction chart. An incorrect taxpayer identifier or payment-recipient name can require different steps from an incorrect amount. Do not mark a correction VOID. For an electronic filing, follow the correction instructions for the IRS system used. Give the payee the appropriate corrected statement.
Does filing federally cover my state return?
Check each relevant state’s rules for the payment year, form and withholding. A payee’s residence, where services were performed or income arose, and where tax was withheld may involve different states. Federal thresholds and an electronic transmission through the Combined Federal/State Filing Program do not establish that every state filing, payment or reconciliation is complete. Document.com supplies the federal PDF only.