Preview the historical form
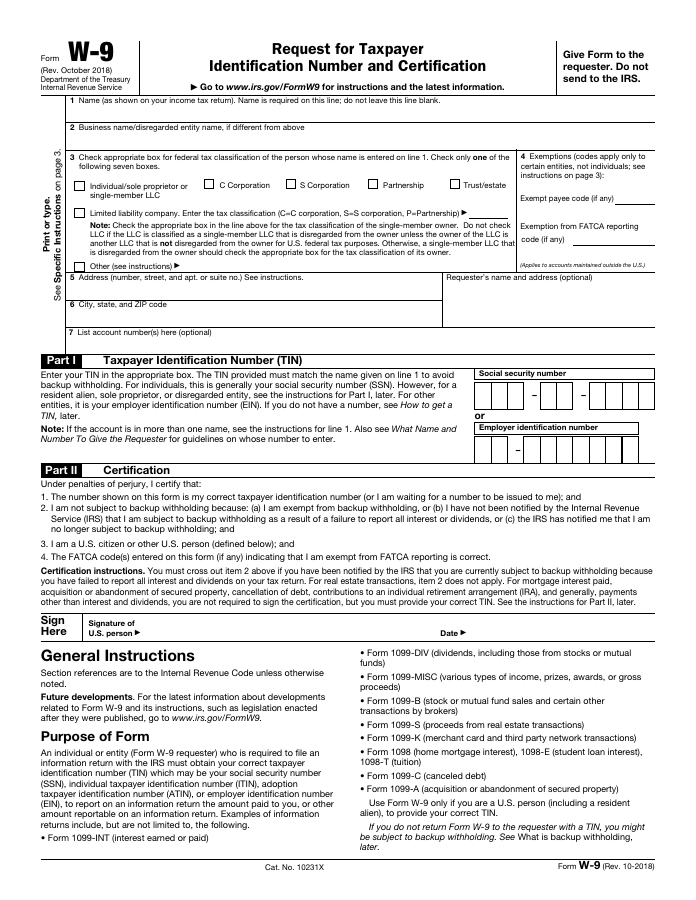 Open the complete IRS PDF
Who should use it?
U.S. persons, including U.S. resident aliens, generally use Form W-9 when a requester needs their TIN for information reporting. A foreign person generally needs the appropriate W-8 series form or, in certain cases, Form 8233. An ITIN alone does not establish tax residency.
Whose name and classification go on the form?
For a disregarded entity, identify the tax owner on line 1 and the entity on line 2. Use the owner’s federal classification and follow the IRS chart for the matching TIN. Partnership, trust, joint-account and foreign-owner arrangements have separate instructions.
What changed after 2023?
The October 2018 edition has no line 3b. The March 2024 revision added a question for certain pass-through owners. Do not add the new checkbox to an archived form.
What am I certifying?
Read Part II before signing. For example, if the IRS has notified you that you are currently subject to backup withholding for underreported interest or dividends, follow the instructions for crossing out item 2. The signature requirements vary by payment or transaction. Give the completed form to the requester, not to the IRS.
What if the TIN is pending or the IRS reports a mismatch?
For certain interest, dividends and readily tradable instruments, a properly signed awaiting-TIN certificate may allow up to 60 days, subject to the IRS conditions. Other reportable payments such as nonemployee compensation generally require immediate backup withholding without a TIN. After a second B notice, another W-9 alone does not resolve the mismatch. See Publication 1281 for the evidence required for an SSN, EIN, ITIN or ATIN.
What if the payer and payee are in different states?
This federal certification does not settle state sourcing, withholding or information-return filing. Those questions may depend on where services were performed or income arose, not just a mailing address. California, for example, distinguishes Form 587 for allocation, Form 590 for eligible exemption claims, and Form 592-B for reporting amounts withheld.