Before you apply
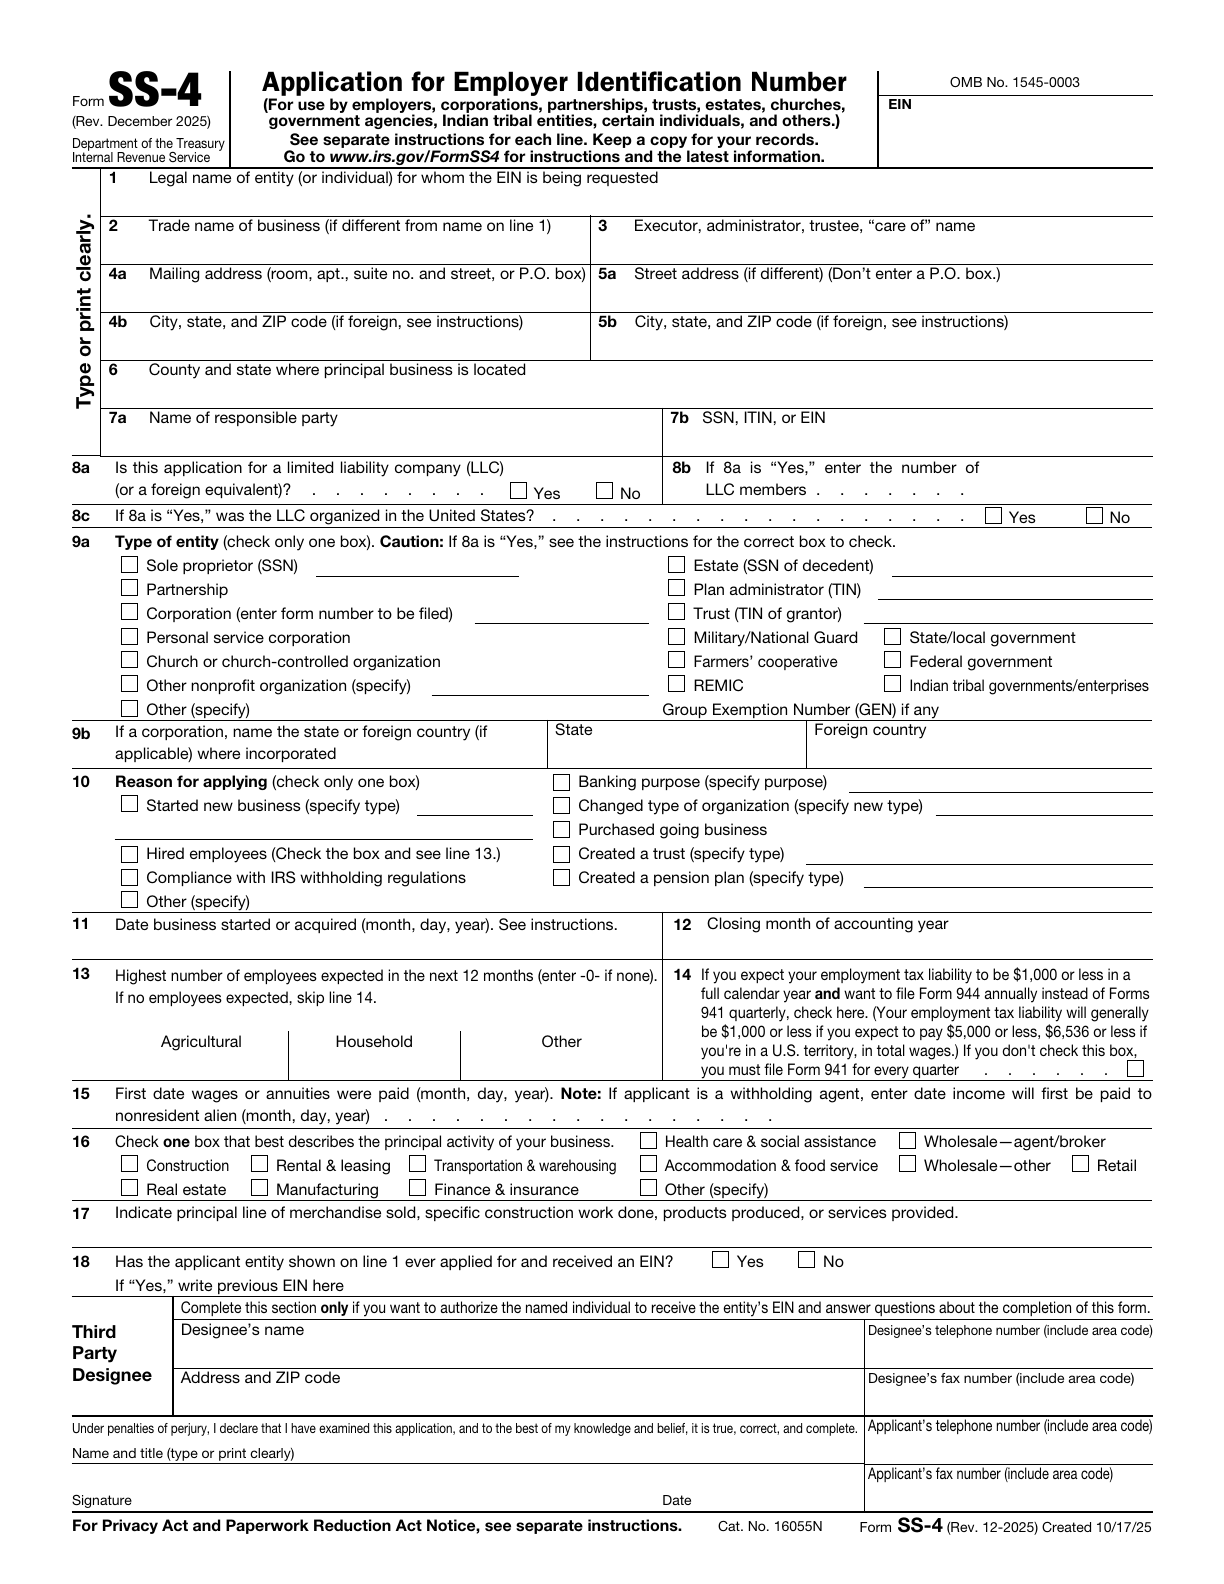
Corporations, partnerships and employers generally need an EIN. Trusts, estates and disregarded entities have their own rules. Page two of Form SS-4 identifies which applicants need a number and which lines to complete. For a new corporation or LLC, complete state formation before applying. If the business already has an EIN, a change of name or location alone generally does not require a new one. A new corporate charter or a change in ownership or structure can change the answer.
IRS eligibility table on Form SS-4 · When the IRS requires a new EIN
Choose a filing method
The IRS online tool checks how and where the organization was formed, its principal place of business, and the responsible party’s taxpayer ID. An eligible applicant can complete the free online application in one session. The session expires after 15 minutes of inactivity. Use the IRS tool to see current eligibility and hours.
If online filing is unavailable, use the IRS instructions to choose fax or mail. Applicants with no legal residence, principal place of business, principal office or agency in the United States or its territories may also apply by international telephone. A U.S. mailing address or registered agent alone does not establish online eligibility. Use one method per entity. The IRS generally issues only one EIN per responsible party per day across all methods.
IRS online tool and hours · IRS fax numbers and mailing addresses · International telephone and signature instructions
Identify the responsible party and any designee
Enter the person who ultimately controls the entity or its assets on line 7a. A nominee who helped form the business cannot be its responsible party. For a trust this is generally the grantor, owner or trustor. For a decedent’s estate it is the executor, administrator or other responsible fiduciary. A government entity follows the IRS’s separate rule.
On line 7b, use the responsible party’s SSN or ITIN as directed. An applicant that is a government entity may use an EIN there. If the responsible party has neither an SSN nor an ITIN and is ineligible for both, enter “foreign” or “N/A” on the paper form. Foreign citizenship alone does not establish ineligibility.
An authorized third-party designee may answer questions about the application and receive the new EIN. The applicant must sign for the designation to take effect. That authority ends when the IRS assigns and releases the EIN to the designee. Separately, an entity must report a change of responsible party to the IRS within 60 days on Form 8822-B.
IRS responsible-party rules · IRS line 7 and designee instructions · Form 8822-B
Enter the formation and business locations separately
The same federal application serves all 50 states and the District of Columbia. Line 6 asks where the principal business is located. Line 9b asks a corporation for its state or foreign country of incorporation. A Delaware corporation operating principally in California would enter its California county and state on line 6 and Delaware on line 9b. Federal EIN issuance does not complete state tax registration, payroll registration or qualification to do business elsewhere.
For an LLC, use lines 8a through 8c for its status, number of members and U.S. organization. On line 9a follow the instructions for its classification and reason for applying. For example, a wholly foreign-owned U.S. disregarded entity obtaining an EIN to file Form 5472 uses the specified “Other” entries on lines 9a and 10. Use the IRS instructions for your entity before selecting a box.
IRS line-by-line instructions · Current IRS revision and updates