What access are you giving?
Form 8821 lets a named person or organization inspect or receive the federal information you identify. It does not grant representation, authority to sign a return, or access to a refund. To authorize representation, see Form 2848. For state tax records, check the state agency’s own process.
Complete the IRS form
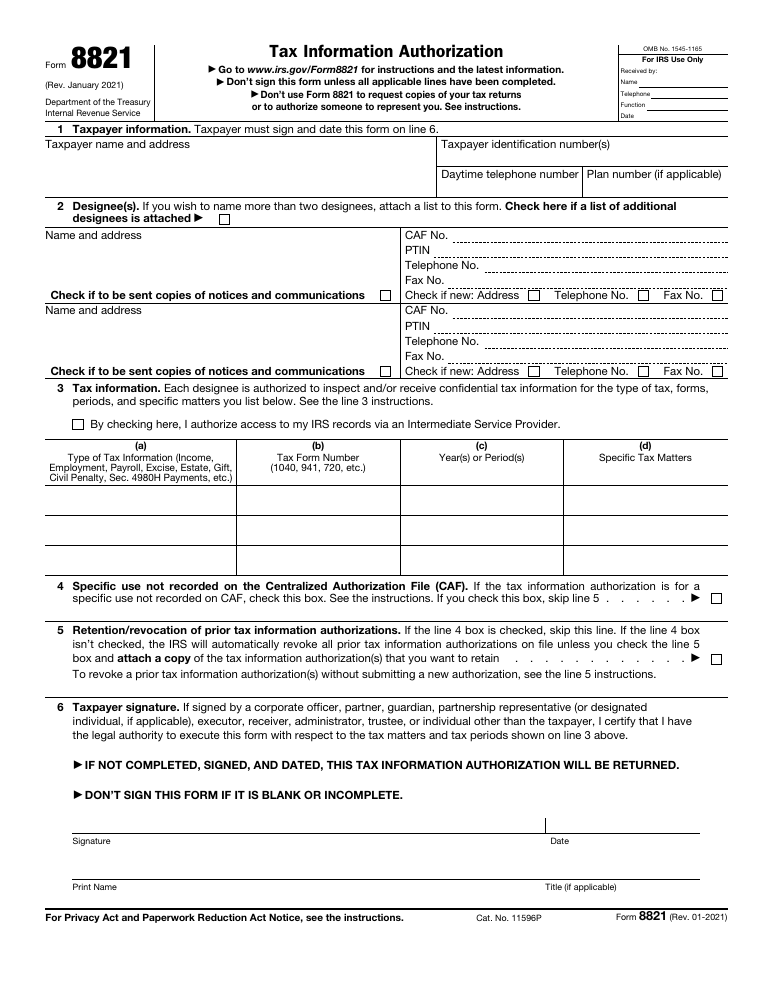
- Identify the taxpayer on line 1. Name your designees on line 2. If you want copies of notices sent to a designee, choose the associated checkbox. You can attach a list for additional designees; only two can receive copies of notices for the same matters.
- On line 3, specify the tax information, form, periods and matters. A blanket entry for all years is insufficient. Grant access through an intermediate service provider only if you intend to give that permission.
- Review lines 4 and 5 before signing line 6. They determine where the authorization goes and what happens to earlier authorizations.
Preview the one-page form
 View the IRS PDF
Signing, filing and keeping prior authorizations
My spouse and I filed jointly. Can we share one authorization?
Each spouse who wants to appoint a designee needs a separate Form 8821. This also applies to former spouses. You may choose different designees or different periods.
What happens to my earlier authorizations?
For an authorization recorded on the IRS Centralized Authorization File (CAF), the IRS revokes prior tax information authorizations on file by default. To keep one, check line 5 and attach a copy of each authorization you want to retain. When line 4 applies, skip line 5; that specific-use authorization does not revoke earlier authorizations.
Where do I send it?
For a specific use outside the CAF, such as disclosure to a lender, use line 4 and send the signed form to the IRS office handling that matter. Otherwise use the IRS online submission option or the mail or fax destination in its current Where To File chart. That chart uses where the taxpayer lives, not where the designee lives. It has separate directions for addresses outside the states and D.C., including military mail.
Can I use an electronic signature?
A form sent by mail or fax needs a handwritten signature. Follow the IRS online submission and identity-verification instructions for an electronic signature. Do not sign a blank or unfinished form.
Does the 120-day rule apply?
For disclosure unrelated to resolving a tax matter with the IRS, such as a lender verifying income, the IRS must receive the form within 120 days after you sign. That receipt deadline does not apply when the authorization is for assistance with a tax matter before the IRS.
Who can sign for a business or estate?
Check line 6 of the instructions for your type of taxpayer and the period covered. A job title alone does not establish authority. The IRS distinguishes officers with authority under applicable state law, board designations and other authorized signers. Partnership, trust and estate requests have their own rules; have supporting evidence of authority available.
Official instructions
Use the IRS instructions for form entries, specific-use requests, filing addresses and how to revoke an existing authorization without naming a new designee. The IRS form page lists the current revision and updates. Complete confidential details directly on the IRS form.